
Introduction: Bhotekoshi floods are an unimaginable natural calamity of the nation. Various immediate, short-term and long-term efforts have been made and will be made for rescue, relief, reconstruction and rehabilitation for this natural disaster. In this context, one of the concessions announced by the government to revive the business establishments and industries damaged by the Bhotekoshi floods is the “Advance Insurance Payment”. Under this, it has been announced that a maximum of 50 percent advance insurance claim payment will be made available immediately to the insured people affected by the floods. Everyone should contribute as much as they can in this time of national calamity. Accordingly, this article briefly highlights the minimum basic facts that the owners, managers and social, political and administrative leaders of the insured business establishments and industries that have suffered losses in order to implement the insurance claim payment declaration of the government.
Quick-Quick Insurance Claim Payment Insurance Company and Surveyor’s Priority:

It cannot be completely ruled out that due to the inefficiency or negligence of the insurance surveyor or the insurance company, the process of settlement of some insurance claims has been delayed and the claimant insured has not received compensation or has not received fair compensation or has been compensated very late. But most of the claims are found to be held up due to the lack of documents required to be provided by the insured and necessary documents to prepare the survey report. Therefore, there is a continuous practice of pressuring the surveyor to call the claimant to provide the necessary documents and the insurance companies to issue public notices in the newspapers to “submit the documents and settle the claim”.
Basic Facts to Consider When Claiming Insurance Claim Payment
In this context, the fact that the general public should keep in mind regarding the payment of insurance claims is that insurance companies are business companies that are standing within the regulatory purview. The general public is not compelled to get insurance in any one insurance company as there is no alternative to the work to be taken from the government agency. Even after providing the information and documents demanded by the surveyor, if the compensation is not received on time or justly, the insurance company is warned by the insured as a customer not to renew the policy or not to buy additional policies from themselves and their associates. The last option is to file a complaint against the insurance company with the concerned regulatory body, the Nepal Insurance Authority, if they are not satisfied with the compensation even after the warning given by the customer.
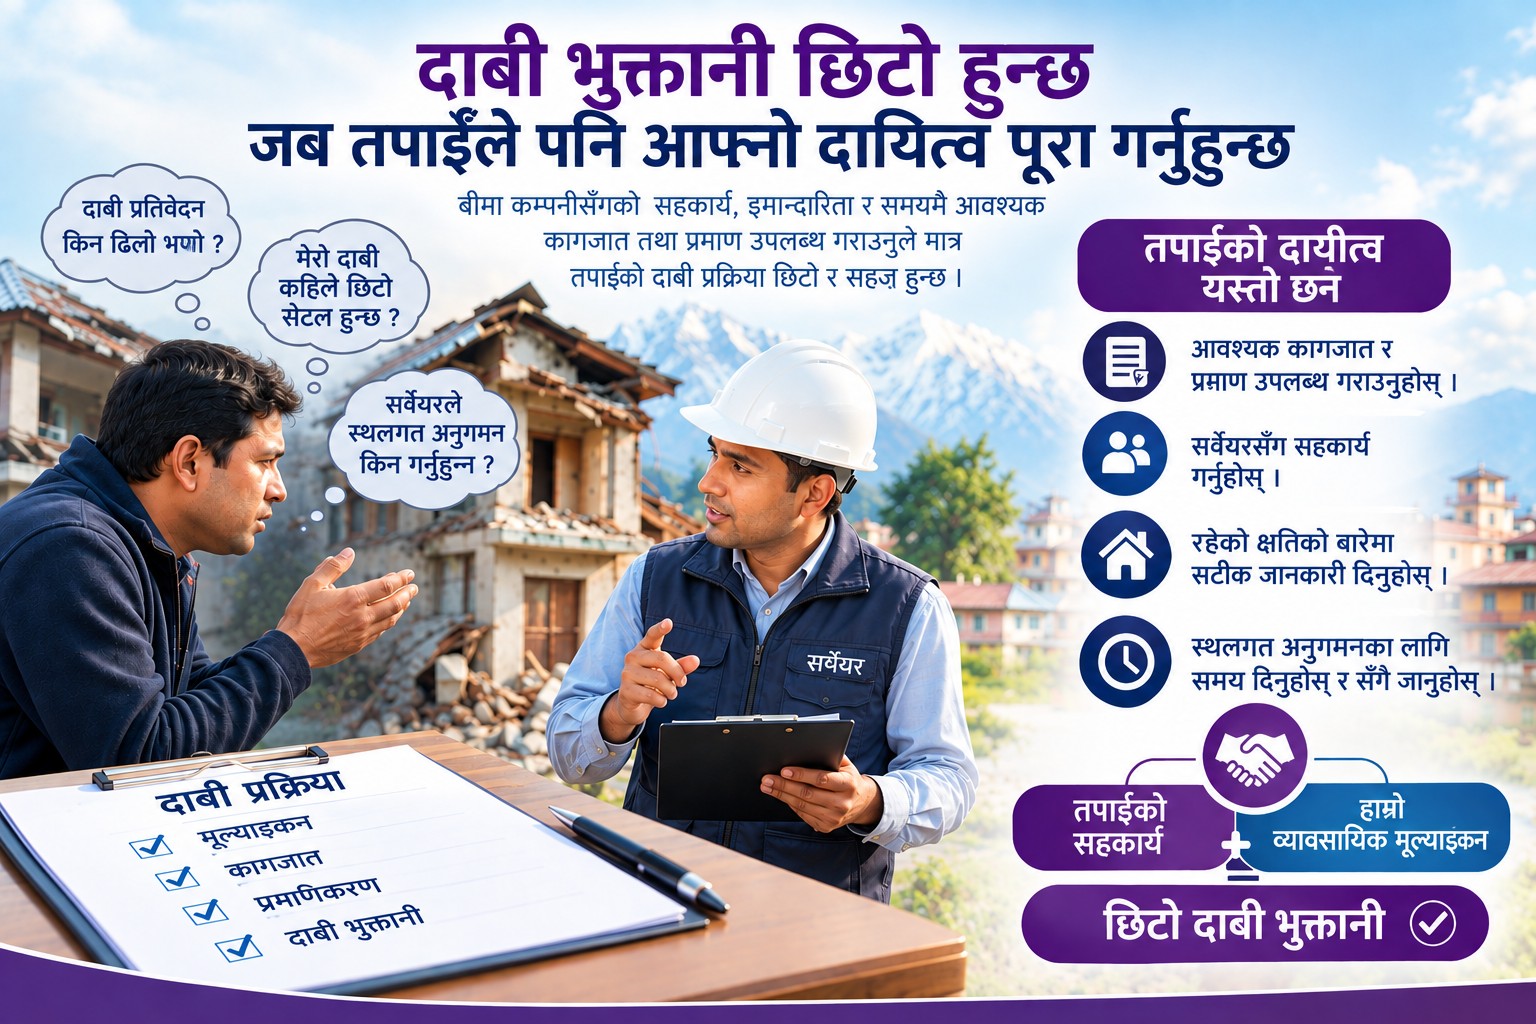
However, some claimant insurers have been pressuring the insured to prepare the damage assessment report instead of providing documents and information to the surveyor to prepare the damage assessment report. Therefore, here are the minimum basic aspects that the claimant insured should know about the documents and information required by the surveyor to prepare the damage assessment report.
Difference in the process of disbursing bank loan and insurance compensation:
}
Some people think of the insurance surveyor as an assessor assigned by the bank and do not give the additional documents demanded by the surveyor and send the report as it is, whatever the insurance company does. But there is a fundamental difference in the process of disbursing the bank loan and insurance compensation.
According to the payment schedule, the bank disburses the loan by taking the mortgage in order to refund the principal amount and the agreed interest amount as well as to cover the loan amount. On the other hand, the insurance company pays the compensation amount on the basis of the surveyor’s report without going through any procedures such as taking the mortgage mortgage and putting a lap on the agreement so that the person receiving the compensation amount is controlled by the bank. Thus, the property valuation report submitted by the valuer of the bank to the bank is only a supporting document for obtaining a bank loan, while the damage assessment report submitted by the surveyor to the insurance company is generally a binding document for the insurance company. Accordingly, in some cases, complaints have been filed with the Insurance Authority of Nepal (TAG_OPEN_em_70 TAG_CLOSE_em_70}} for not getting compensation from the insurance company as per the damage assessment report submitted by the surveyor.
Since the insurance company has to submit a mandatory type of damage assessment report, the surveyor has a serious responsibility on the survey report. Accordingly, the surveyor can prepare the damage assessment report only after making an assessment about the aspects of whether compensation can be paid for the claim or not and how much amount should be paid. Therefore, the discussions and activities for the purpose of making quick compensation should be focused on the basic aspects of the damage assessment report prepared by the surveyor.
Aspects of whether or not compensation should be awarded and how much money should be paid
When there is a deputation for a survey from the insurance company, usually only the application of the insured and the insurance policy are received by the surveyor. Therefore, at the time of receipt of the work order, the surveyor is unaware of the aspects of whether or not compensation can be paid for the claim and how much money should be paid. The surveyor ascertains these aspects only with the help of the claimant insured. Depending on the type of claim, the surveyor can prepare a damage assessment report and recommend compensation only after confirming various aspects including the following.
- Function to confirm the actual physical existence of the insured property
- Assessing the amount of insured stock
- Tasks to verify on-site details written in insurance policy
- Other actions to be determined by type of insurance
- Determining who should be compensated for a related claim (insurable interest)
- Function to verify other aspects specified by the property insurance policy
}
Actual On-Site Presence of Insured Property ({{Physical Existence):
The surveyor has to prove on the spot whether the shop, house, machine or vehicle mentioned in the insurance bill was actually in existence or not. In a village in Sindhupalchowk, where it was difficult to ascertain the plot number during the earthquake, even though the insured house was safe, another uninsured damaged house was shown in the same locality and the surveyor was deceived and compensation was recommended. At that time, there were many complaints of such fraud. After the last year’s Roshi floods, a crusher on the banks of the Roshi river cut and sold two of his excavators and sold them, after which a complaint reached the Patan High Court claiming that the excavators were swept away by the floods. Therefore, the claimant should extend all possible help to the surveyor to establish the case that the insured property is missing. However, some claimants do not cooperate with the surveyor by accusing them of “ and ?” without realizing the responsibility of the surveyor.
Assessing the amount of insured stock:
}
Both on the basis of physical basis and on the basis of the documents submitted, the surveyor has to prove the quantity of damaged stock claimed. For the physical basis, the measurement of the shop warehouse is done. For the basis of the documents, the audit report, stock report, bank transaction etc. are demanded and studied. If both these grounds are found to be insufficient to assess the quantity of insured stock, then the surveyor should also enquire about the quantity of stock in the damaged shop/godown even from the neighbourhood of the shop/godown. The surveyor has to create a situation in the report to be able to answer the question “On what basis the amount was recommended” during the inspection of the damage assessment report. For this, the surveyors submit the damage assessment report only after deciding to face the question by using various tricks.
Functions to verify on-site details written in insurance policy:
The details about the insured person/institution, the insured property and various other details are written in the concerned insurance article. The surveyor has to verify these details on-the-spot and write as “as written in the insurance policy”. There are various difficulties in this direction such as
- The name of the municipality, ward number, toll, and plot number are written on the place where the insured property is located. Since some insureds do not inform the insurance company about the relocation of their shop or store, the place where the stock is written in the insurance article and the place where the stock is damaged are different. In such a case, the surveyor naturally has to write “The place where the stock is located and the place where the stock is damaged in the insurance policy” – which is the situation in which the claimant insured does not get compensation.
- Recently, in the fire of a jewelry shop, the insurance claim was made as the gold and silver ornaments of the shop were intact and only the decoration and furniture of the shop were damaged. However, since it was clearly mentioned in the insurance policy that only the gold and silver ornaments were covered by the policy, the surveyor had to write that the damage to the decoration and furniture of the shop was not covered by the policy.
- Within 35 days of the transfer of the vehicle, the insurance policy should also be transferred in the name of the new vehicle owner, otherwise the claim will not be made, the fact is clearly mentioned in all the vehicle insurance policies. However, some vehicle buyers who buy from individuals or re-conditions are found to see the insurance policy only after the incident. It is a clear and irreversible condition that the vehicles that are not enrolled in the insurance policy do not get compensation. Accordingly, the surveyor cannot recommend compensation in the survey report of the insurance claim of the vehicles which are not enrolled in the insurance policy and such vehicle owners allege that the insurance company and the surveyors have not paid compensation intentionally.
In this way, the surveyor can recommend compensation only after determining the various minimum aspects, including whether or not compensation can be given for the claim, and how much money should be paid. If the survey report recommends compensation without determining such minimum aspects, then the surveyor himself can be a part of the action of the Nepal Insurance Authority.
Role of Claim-Related Parties for Faster Insurance Claim Payment:
It is found that the owners, managers and social and political leaders of the insured business establishments and industries have been repeatedly contacting the insurance company and putting pressure on the insurance company to get compensation to the victim. Instead, the insurance surveyor should coordinate with the insurance surveyor to gather the necessary documents and information. If the surveyor does not come in contact, the surveyor asks for inappropriate documents and information, or otherwise harasses him, he should take the help of his insurance company to solve the problem. The Insurance Act provides that if there is a serious error or negligence in the work done by the surveyor, a complaint can also be filed with the Nepal Insurance Authority, the body that licenses the surveyor.
Conclusion: As mentioned above, instead of collecting the documents and information requested by the surveyor, there is a growing tendency to put pressure on the insurance company and put pressure on the surveyor in various ways. To discourage such a trend, the Insurance Authority of Nepal and the insurance companies should increase the activities to increase the awareness among the insured about the non-life insurance claim process. In the absence of this awareness, it is challenging to implement the announcement of early insurance claim payment or full insurance claim payment. It is necessary for the concerned parties to be aware of this.
(The author is an insurance surveyor)